
BILL AP & AR Business Payments
- Rating
- 4.3
- Downloads
- 500.00K
- Content Rating
- Everyone
BILL AP & AR Business Payments - Screenshots
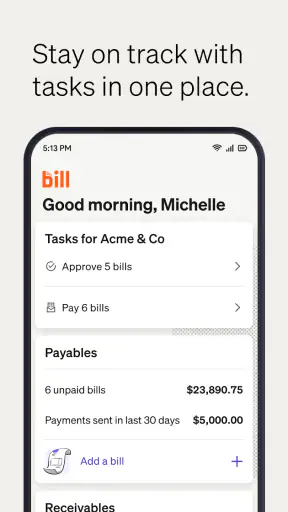
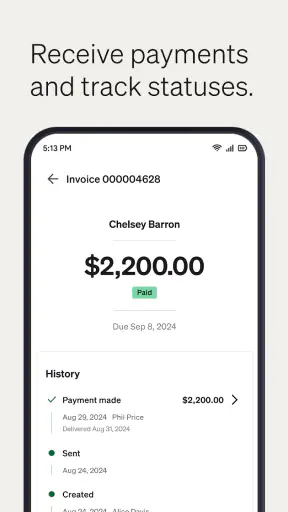
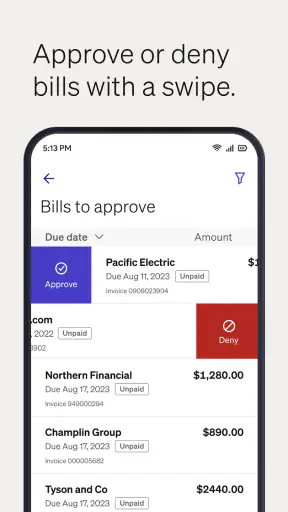
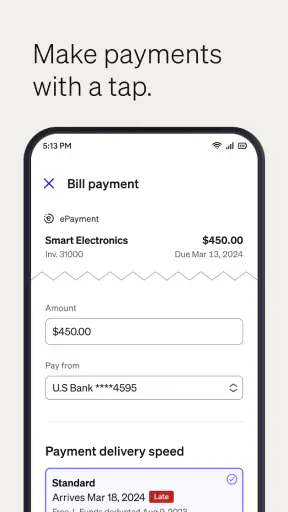
Pros
- Streamlines invoice creation
- tracking
- and payment management in one place.
- Helps businesses maintain clearer records of accounts receivable and payable.
- Can reduce manual data entry and improve payment workflow efficiency.
- Useful for monitoring outstanding invoices and upcoming business obligations.
- Designed to support more organized financial administration for growing businesses.
Cons
- May require setup time before payment and invoice workflows run smoothly.
- Advanced features may be more useful to established businesses than individuals.
- Users may need accounting knowledge to configure financial processes correctly.
- Payment availability and supported methods can vary by region or account type.
- Businesses should verify security
- fees
- and integration details before relying on it.
BILL AP & AR Business Payments - Description
- App Name
- BILL AP & AR Business Payments
- Package Name
- com.bdc.bill
- Developer
- Bill.com Inc.
- Category
- Business
- Last Updated
- Dec 16, 2015
- Version
- 3.7.171
Managing bills and incoming payments from a phone sounds simple until invoices, approvals, reminders, and records start competing for attention. BILL AP & AR Business Payments is a free business app from Bill.com Inc. that focuses on that exact space: helping businesses handle accounts payable and accounts receivable activities online rather than treating every payment as a separate manual task. I see it as a practical companion for people who already work with BILL’s business payment workflow and want access while away from a desk, rather than as a complete replacement for accounting software.
My first impression is that the app makes most sense when payments are part of a shared business process. A freelancer with only a few monthly bills may find a banking app or a simple spreadsheet easier. A small company that regularly receives invoices, pays vendors, and needs a clearer view of outstanding money has a stronger reason to consider it. The distinction matters because the app’s value is not just in sending or receiving a payment; it is in bringing those activities into a more organized business routine.
How BILL AP & AR Business Payments fits into daily work
A business-focused tool rather than a personal bill payer
The name can be read quickly as a general bill-paying application, but the AP and AR focus points to two sides of business finance. Accounts payable covers money a company owes, while accounts receivable covers money customers owe the company. That makes this a different proposition from a consumer banking app, where the main goal is usually to pay household bills or move money between personal accounts.
In my view, this distinction is one of the most important things to understand before installing it. The app is aimed at business payments, so its usefulness depends on whether your work involves vendors, invoices, customers, or approval responsibilities. If you are looking for a personal budgeting tool, expense tracker, or everyday banking replacement, this is probably the wrong category.
The developer is Bill.com Inc., and the app has been available since December 16, 2015. Its current version is 3.7.171, and it requires iOS 9 or later. Those details make it accessible to users who are not running the newest device software, although I would still keep the operating system updated where possible for general security and compatibility reasons.
What the free price means in practical terms
The app itself is free to install, which removes the initial cost barrier for a business owner, bookkeeper, or team member who wants to try the mobile experience. That is useful when the immediate question is whether mobile access fits an existing workflow. You can evaluate the app without treating the download as a separate purchase decision.
Still, free access should not be confused with a promise that every business payment service connected to the broader platform is free. The confirmed price describes the app, not every possible account arrangement, transaction condition, or business service. I would check the terms that apply to your BILL account before making a financial decision, especially if payment volume or business-critical processing is involved.
That is a valuable trade-off: the app can be easy to test, but the overall cost of using a business payment platform may depend on the service relationship around it. I would not choose it solely because the download costs nothing. I would choose it if the workflow saves enough time or reduces enough payment confusion to justify the wider arrangement your company uses.
Where the app can save time
The strongest value comes from reducing the distance between noticing a payment task and acting on it. A business owner may be away from a computer when a vendor invoice needs attention. A manager may need to review a payment-related item while traveling. A person responsible for receivables may want to check what still needs follow-up without waiting until the end of the day.
Mobile access is especially helpful for short decisions. Instead of opening a laptop just to inspect the next task, I can imagine using the app during a commute break, between appointments, or after a supplier sends a reminder. That does not turn a phone into a full accounting department, but it can prevent small payment tasks from sitting untouched until they become urgent.
A useful habit is to separate quick mobile actions from deeper financial work. I would use the phone for checking the status of a payment-related item, responding to a time-sensitive task, or keeping the queue moving. I would reserve reconciliation, reporting, and complicated bookkeeping decisions for a larger screen and the accounting tools that support them. That division makes the app more useful and avoids expecting too much from a mobile interface.
A realistic small-business scenario
Imagine a small design studio that receives invoices from contractors and sends invoices to clients. The studio owner spends much of the week visiting customers, while a bookkeeper handles routine finance work. A vendor follows up about an unpaid invoice during the owner’s afternoon. With a business payments app available, the owner can deal with the relevant task sooner instead of forwarding a message and hoping it is handled before the next payment run.
On the receivables side, the same owner may want to keep an eye on money expected from clients while deciding whether to approve a new purchase. That context can make a payment conversation more useful than a simple bank balance. The app does not replace financial judgment, but it can make the operational side of that judgment more immediate.
The hidden benefit in this scenario is not speed alone. It is the reduction of handoffs. When payment work moves between an owner, bookkeeper, and other team members, delays often come from uncertainty about who should act next. A mobile view can help the responsible person stay connected to the workflow, though the business still needs clear internal rules about approvals and follow-up.
Useful habits for accounts payable
For outgoing payments, I would treat the app as a queue-management tool rather than a place to make rushed decisions. Before approving or handling anything, I would check the vendor name, invoice context, amount, and timing against the company’s normal records. A phone is convenient, but its small screen can make it easier to overlook a detail than when reviewing a document on a desktop.
One practical workflow is to use mobile access for triage. I would identify which items are routine, which need another person’s approval, and which require a closer document review. Routine items can keep moving, while unusual requests should wait for verification. This is particularly important when a payment request arrives with changed bank details or an unexpected amount; convenience should never override the company’s verification process.
Another useful approach is to avoid leaving every decision until a single weekly session. If the app helps me notice pending work earlier, I can resolve straightforward items in smaller batches. That may reduce the chance of missing a due date, while still leaving complex exceptions for a more careful review.
Useful habits for accounts receivable
Incoming money requires a different mindset. It is not enough to know that a customer owes the business; the team also needs a consistent follow-up process. I would use the app to stay aware of receivables activity, then pair that awareness with a simple schedule for contacting customers, checking disputed invoices, and updating internal notes elsewhere when deeper context is needed.
A non-obvious strength of mobile access is that it can improve timing in customer conversations. If a client asks about an invoice during a meeting, having a current view of the relevant payment situation is more useful than promising to investigate later. That can make the business appear more organized, but I would still avoid quoting details from memory when the invoice or customer record needs a full review.
For businesses with uneven cash flow, receivables awareness can also influence purchasing decisions. Seeing that expected customer payments are delayed may encourage a manager to postpone a nonessential expense or contact the customer sooner. The app does not create cash flow, but it can help the team react before a small delay becomes a larger planning problem.
How it compares with familiar alternatives
The most obvious alternatives are a bank’s business app, an accounting package, email, and spreadsheets. A bank app is usually better for viewing balances and completed transactions. It may be the right choice when the only task is moving money or checking whether a transfer arrived. It is less naturally suited to coordinating invoice-related work across a business process.
An accounting package is generally stronger for the full financial picture: bookkeeping, reports, reconciliation, and tax preparation. If those are your main needs, BILL AP & AR Business Payments should be viewed as a focused payment companion rather than a replacement. The advantage of the focused approach is that it can keep payment work more visible; the disadvantage is that you may still need another system for the records around it.
Email and spreadsheets remain attractive because they are familiar and flexible. A very small operation may manage a modest number of invoices with those tools at little direct cost. The weakness is that responsibility can become unclear, versions can drift, and payment status may depend on someone remembering to update a cell or search a message thread. The app becomes more compelling as the cost of that informal system grows.
I would also distinguish it from a personal payment app. Consumer services often optimize for speed between individuals, while business payments require vendor context, customer follow-up, and internal accountability. Choosing a personal tool for company payments may feel convenient at first but can make records and ownership harder to manage later.
Where the mobile format creates friction
The phone format is both the reason to use the app and one of its limitations. A compact screen is convenient for quick checks, but less comfortable for reading long invoice details, comparing multiple records, or investigating an unusual payment. I would not want a team to make every high-value or ambiguous decision from a phone simply because the app makes it possible.
There is also a human limitation: mobile convenience can encourage reactive finance work. A notification or urgent message may push someone to approve an item without following the company’s normal checks. The app can shorten the route to action, but it cannot supply good internal controls. Businesses should decide in advance which actions are suitable on mobile and which require desktop review or another person’s approval.
Another trade-off is that a payment workflow is only as reliable as the people using it. If the owner, bookkeeper, and approver do not agree on responsibilities, adding a mobile channel may create more places to look rather than more clarity. I would establish a simple rule for who monitors incoming tasks, who approves them, and where exceptions are discussed.
Who is likely to get the most value
I think the app is a good fit for small and midsize businesses that already depend on structured accounts payable or accounts receivable work and want mobile access to that process. Owners who travel, bookkeepers who need to keep work moving, and managers who approve business payments are the most obvious candidates.
It can also suit a company that has outgrown email-based payment coordination but does not want every employee working directly inside a bank account. The focused payment workflow may make responsibilities easier to separate, particularly when several people touch the same invoice cycle.
The free download makes experimentation straightforward, so a sensible test is to use it during one ordinary payment cycle. Pay attention to whether mobile access actually reduces delays, whether the team understands who should act, and whether the phone view is detailed enough for the decisions you expect to make. Those answers are more useful than judging the app only by its installation experience.
Who should probably skip it
I would skip it if you only need personal bill payment, household budgeting, or a basic way to check a bank balance. Those jobs are better served by tools designed around personal finance. I would also hesitate if your business has no recurring vendor or customer payment workflow; the AP and AR focus may add structure you do not need.
Businesses looking for a complete accounting system should be cautious about treating this app as the whole solution. If reporting, reconciliation, payroll, inventory, or tax work is central to your search, a full accounting platform is likely a better primary choice. The app may still have a role beside that system, but it should not be expected to cover every financial function.
Finally, companies with strict desktop-only approval policies may gain little from mobile access. The app’s convenience matters only when the organization is prepared to use it responsibly. If every action must wait for a desktop review, the phone installation may become an extra notification channel rather than a meaningful improvement.
What the adoption numbers suggest, and what they do not
The app has an average rating of 4.3 from around 7,500 ratings, with roughly 1,500 written reviews, and it has passed 500,000 installs. Those figures suggest that it has reached a substantial audience and that many users find the product useful enough to rate. They are encouraging signs for a business app that depends on repeated, practical use.
I would still read the reviews with a specific question in mind: do they describe the same business workflow you need? A positive experience from someone checking routine payment tasks may not answer the concerns of a company with complicated approval rules. Ratings are helpful for spotting recurring friction, but they cannot decide whether the app fits your organization’s process.
The Everyone content rating is reassuring for general accessibility, but it is not a substitute for evaluating business suitability. Age classification describes the type of content presented, not whether the app has the controls, detail, or workflow depth your finance team requires.
My practical way to evaluate it
I would begin by identifying one narrow job: keeping up with outgoing invoice tasks while away from the office, or checking receivables during customer meetings. I would avoid changing the entire finance process on the first day. A focused trial makes it easier to see whether the app removes a real bottleneck or simply duplicates information already available elsewhere.
Next, I would compare the time between receiving a task and assigning or completing it before and after mobile use. I would also note how often I need to switch to a desktop, search email, or ask another person for context. Those observations reveal the app’s actual value more clearly than the number of available screens.
My final check would be control and clarity. Can each team member explain what they are responsible for? Are unusual payment requests being verified? Does the business know where supporting information belongs? If the answers are no, the solution is a better process first and a new app second.
My verdict on the value
BILL AP & AR Business Payments is worth trying when mobile access can keep a real business payment workflow moving. Because the app is free to install, the initial decision is low-risk, but the broader value depends on how well it fits your company’s BILL setup and payment habits. I like it most as a focused companion for AP and AR work, not as a universal finance app.
Its best use is practical: review payment-related work between meetings, respond to routine tasks sooner, stay aware of incoming money, and reduce unnecessary handoffs. Its main weakness is equally practical: a phone is not the ideal place for every detailed or high-consequence financial decision. The right balance is to use mobile access for visibility and timely action while keeping deeper review and accounting work in the appropriate desktop or financial system.
For a business already organized around Bill.com Inc.’s payment services, I would recommend testing it with a defined workflow and clear approval rules. For a personal user, a company seeking full accounting software, or a team with no need for mobile payment access, I would skip it and choose a tool built for that specific job. That makes the free app valuable for the right audience without pretending it is the answer to every finance problem.
FAQ
What is BILL AP & AR Business Payments used for?
BILL AP & AR Business Payments is a business finance platform designed to help companies manage accounts payable and accounts receivable in one place. After reviewing its workflow, the main purpose is to let businesses pay bills, send invoices, receive payments, monitor transaction status, and keep financial administration more organized than using email, spreadsheets, and separate payment tools.
Is BILL AP & AR Business Payments suitable for small businesses?
Yes, the platform can be useful for small and growing businesses that want to reduce manual payment work and improve cash-flow visibility. It is especially helpful when several people need to approve bills or track incoming payments. However, users should review the available plans, transaction fees, supported payment methods, and accounting integrations before deciding whether it fits their company’s size and budget.
Can I connect BILL with accounting software and business bank accounts?
BILL is designed to work alongside common accounting and financial workflows, allowing businesses to connect relevant accounts and synchronize payment or invoice information where supported. The exact integrations and available features may depend on the user’s country, subscription, and account type. Before downloading or subscribing, check the current integration list to confirm compatibility with your accounting software and bank.
Is BILL AP & AR Business Payments secure for sending and receiving money?
The service includes business-focused security and permission features intended to protect financial information and reduce unauthorized activity. Depending on the account setup, users may be able to assign roles, create approval workflows, and review payment activity. Even so, security also depends on the company’s practices, so enable multi-factor authentication, use strong passwords, verify payment details, and limit access to trusted employees.
Are there fees for using BILL AP & AR Business Payments?
BILL may charge fees depending on the selected product, payment method, subscription, and transaction type. Some features can be included in a plan while expedited payments, card payments, international transactions, or other services may have separate costs. Pricing can change and may vary by location, so businesses should consult the official pricing information carefully before creating an account or moving regular payments to the platform.


